Ice cream, without shortcuts.
The deck describes 16 core staples made with fresh ingredients, without additives, emulsifiers, or thickeners, supported by an ongoing pipeline of artisan flavor drops.
Premium ice cream and coffee. A Harlem launchpad. A plan to turn cultural connection into a scalable consumer brand.

Ice cream delivers indulgence. Coffee creates a ritual. Sugar Rays brings both under one premium, culturally distinctive brand.
The initial focus is New York City: a concentrated market for retail, delivery, activations, and early packaged-goods distribution.
The source deck projects 2034 global ice cream revenue of $125–165 billion and coffee revenue of $395–445 billion. These figures provide context, not Sugar Rays sales forecasts. Supporting sources and assumptions remain to be supplied.


A complementary pair of products built around craftsmanship, flavor, and repeat purchase.
The deck describes 16 core staples made with fresh ingredients, without additives, emulsifiers, or thickeners, supported by an ongoing pipeline of artisan flavor drops.
Sourcing relationships in Ethiopia, Jamaica, and Colombia, roasting partners, and skilled preparation support a premium coffee experience.
Premium yet accessible is the intended positioning. Working prices include a $5.95 scoop, $7.99 16 oz pint, $4.95 hot latte, and $2.75 classic cookie. These are management pricing assumptions; selected product costs and variable margins appear in Financial Potential. Product specifications, supplier quotes, and packaging claims remain subject to validation.
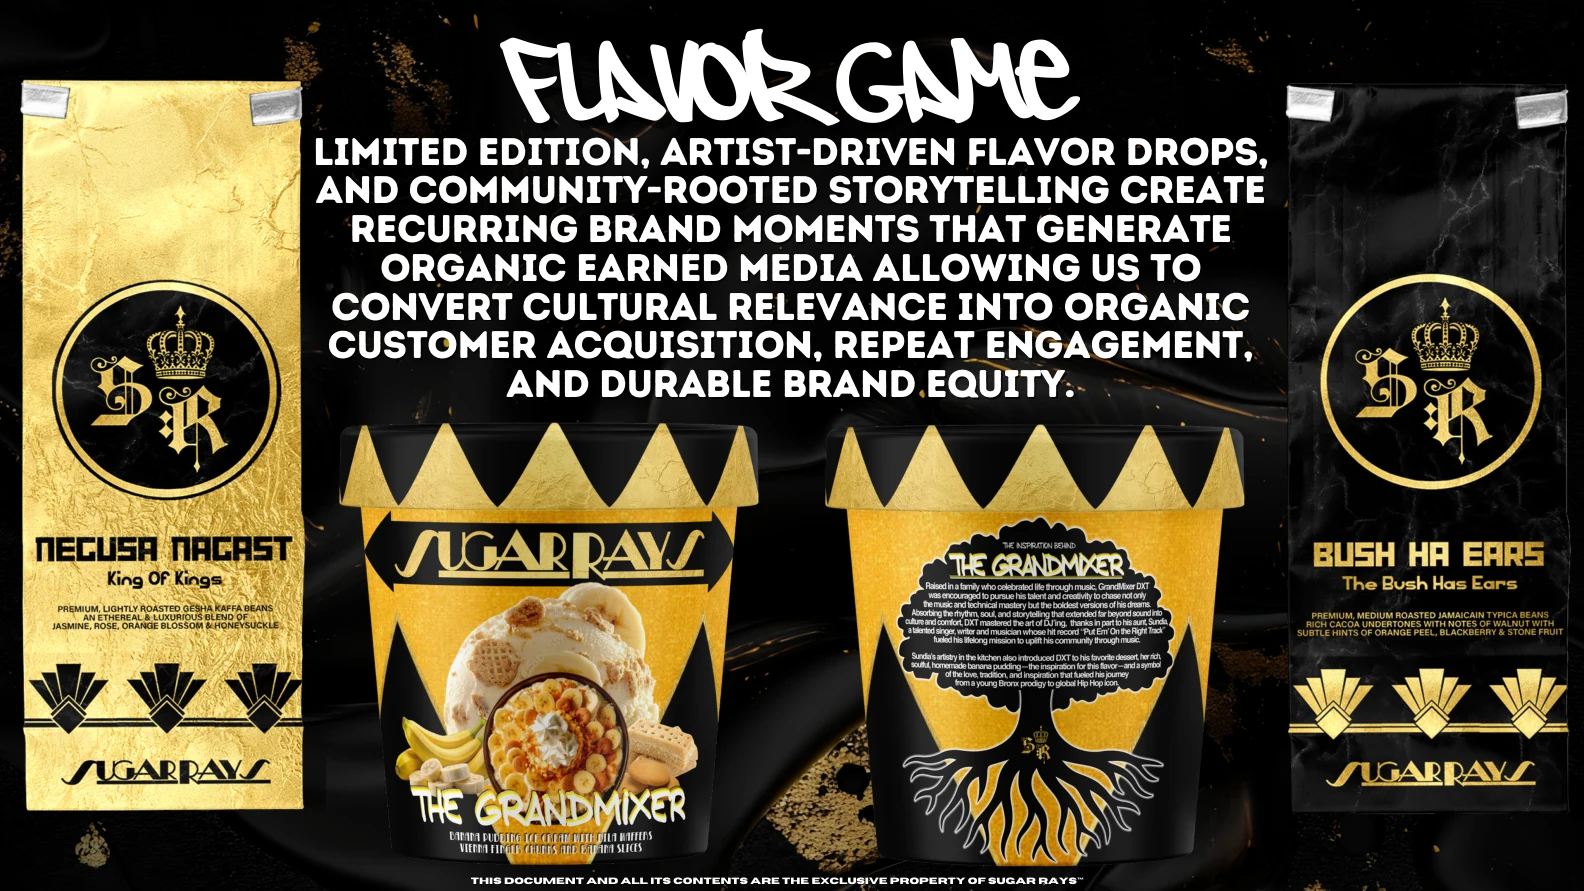
Sugar Rays combines a crown identity, bold flavor colors, and graffiti-inspired lettering with the brand’s roots in Hip Hop.
The packaging provides a consistent visual system; limited-edition collaborations create new stories within it.
The crown expresses status; arrows reference graffiti writers; ingredient imagery identifies flavors; patchwork and rocker elements reference street culture and early Hip Hop fashion. These details reinforce recognition across ice cream and coffee.
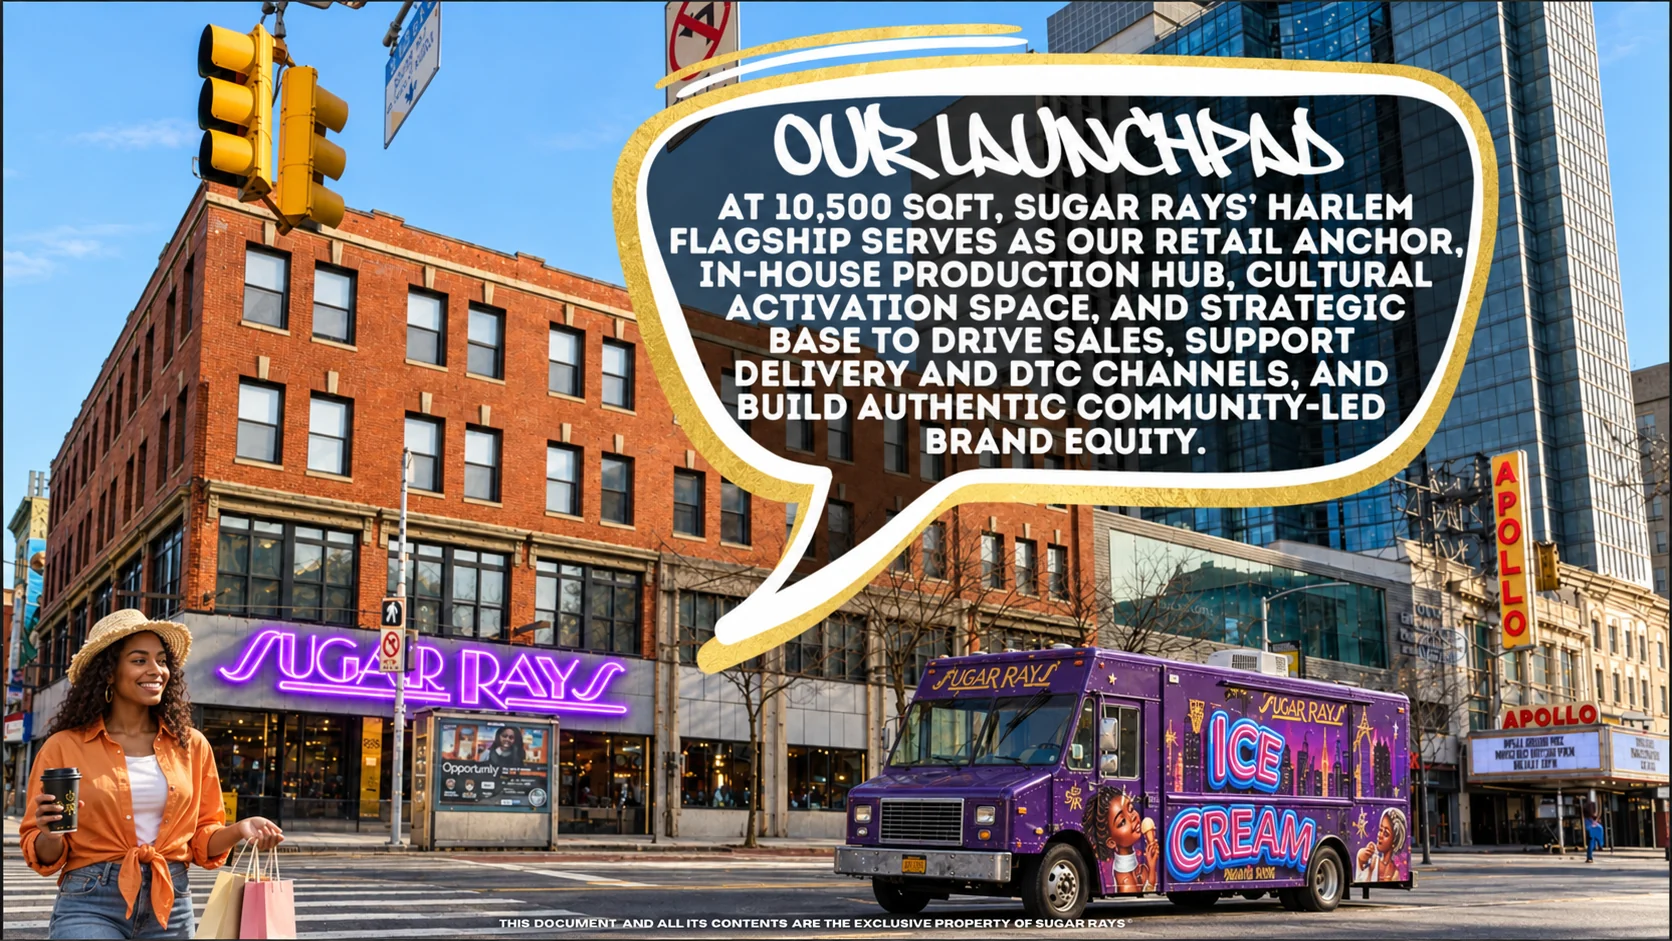
Planned Harlem flagship
A retail anchor, in-house creamery, distribution base, and cultural activation space.
Ice cream and coffee service.
Production supporting retail and packaged goods.
Delivery and direct-to-consumer distribution.
Events and collaboration spaces.
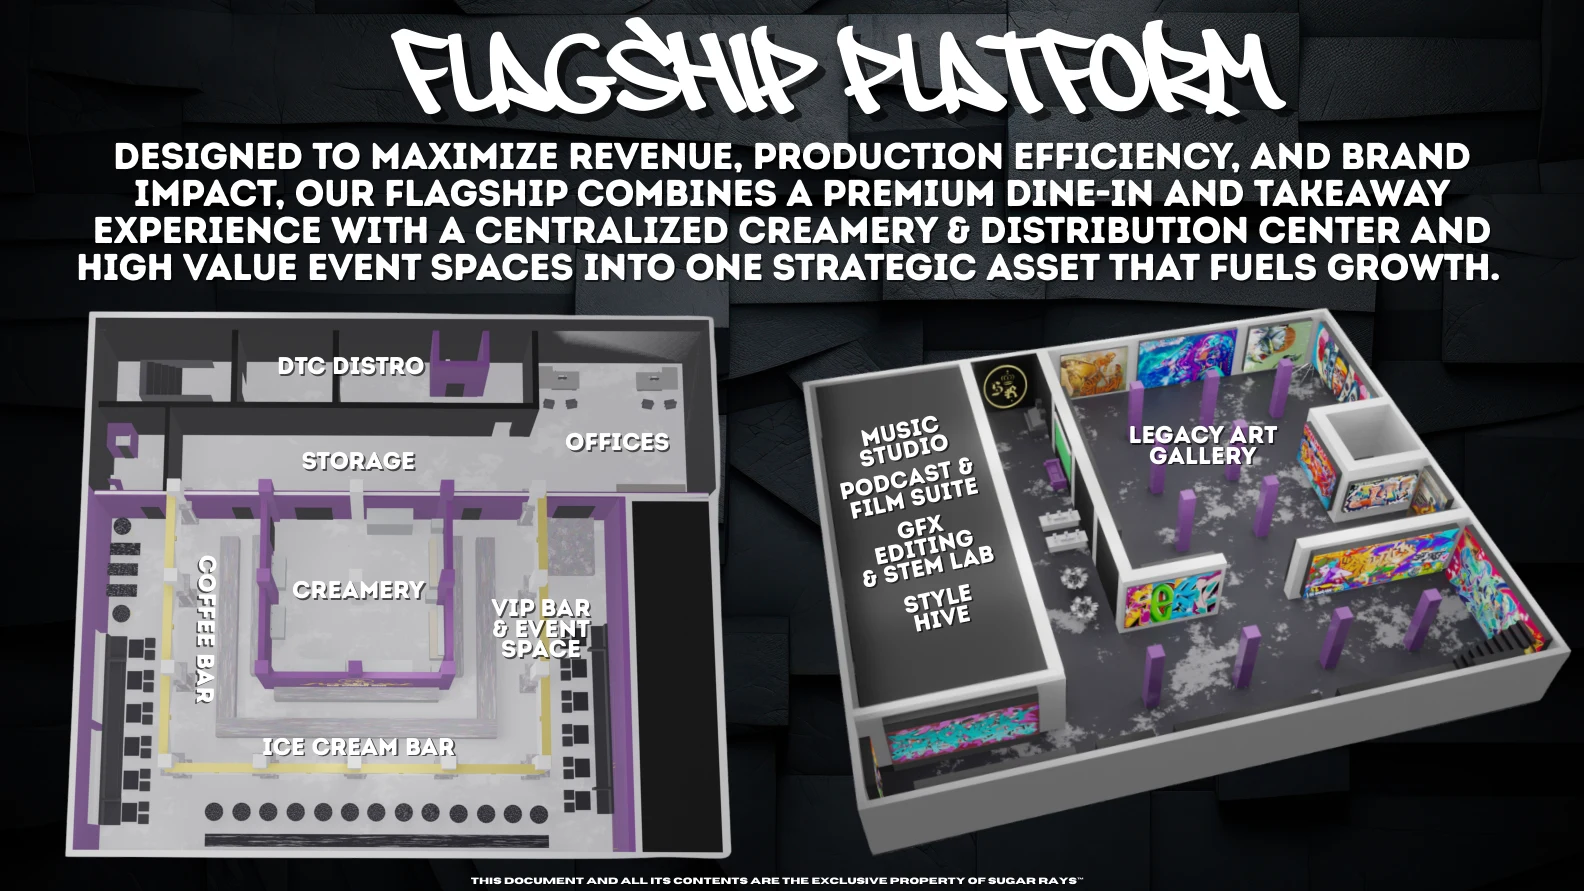
The deck includes VIP/event space, offices, art gallery, and creative production areas. Management targets a March 2027 production / DTC / truck soft launch and a July 2027 flagship grand opening, with approximately $1.2M gross buildout and production-equipment planning capital. Lease terms and construction bids remain subject to validation. Images represent the supplied concept.
The plan combines direct customer sales with distribution channels that can expand beyond the flagship.
Ice cream and coffee sold through the flagship and future satellite locations.
Local delivery and direct-to-consumer channels supported by the production hub.
Early grocery entry with co-packer support, followed by broader retail distribution.
Mobile sales, events, and collaborative merchandise as additional revenue opportunities.
The October 2026 plan adds pre-launch restaurant placements to the revenue model. FY1–FY5 financials are management projections; realized sales and verified channel contribution margins are not supplied.
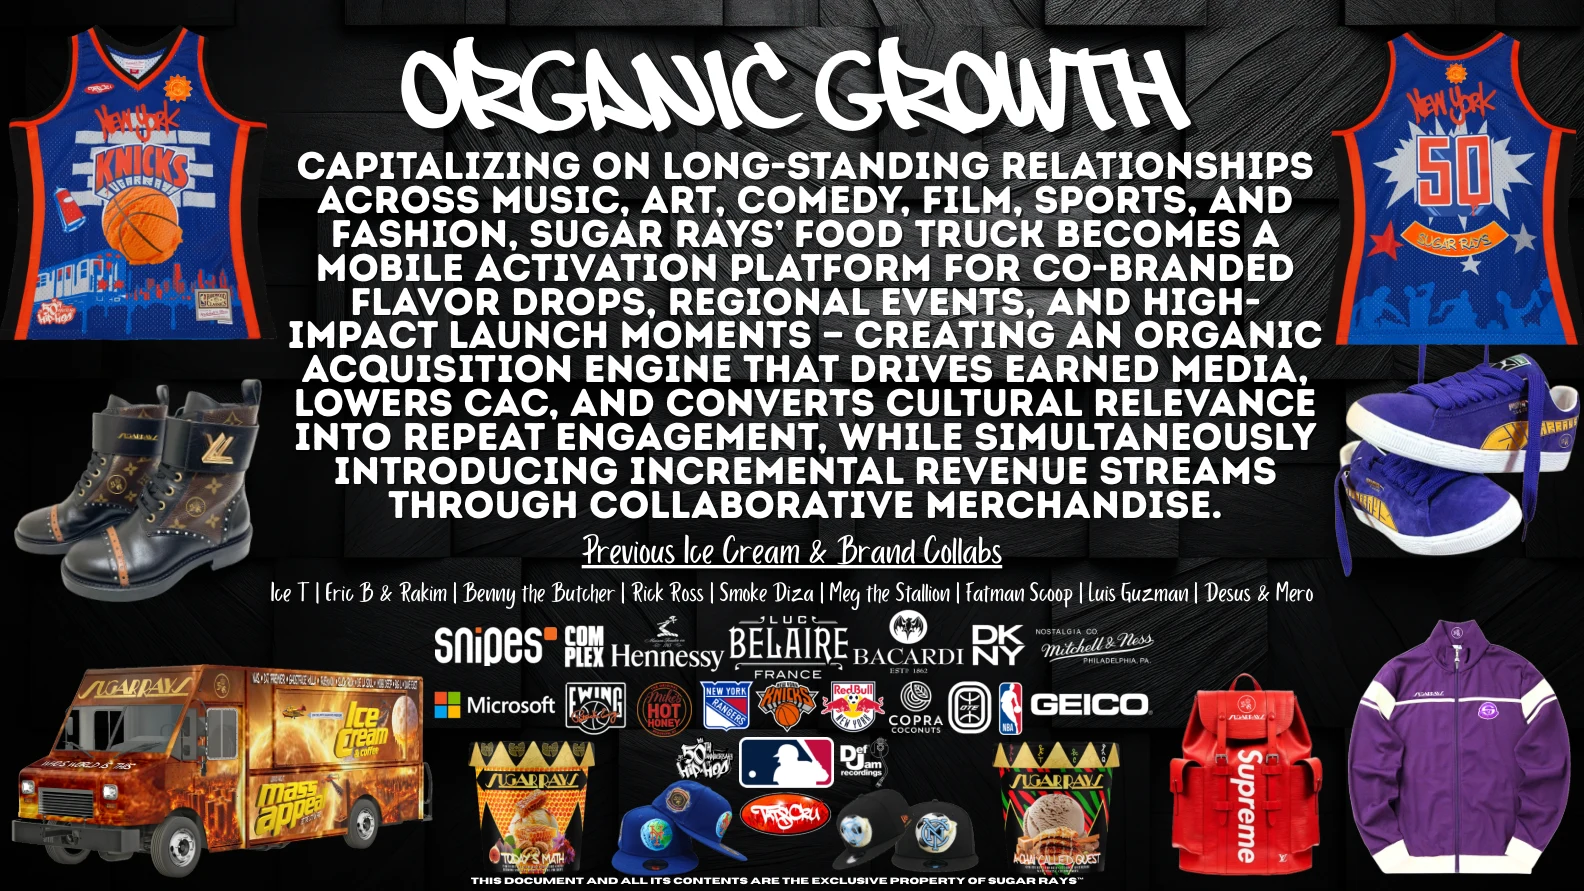
Artist-driven flavor drops and mobile activations turn partnerships into recurring brand moments.
The source deck lists previous ice cream and brand collaborations involving Ice T, Eric B & Rakim, Benny the Butcher, Rick Ross, Smoke DZA, Megan Thee Stallion, Fatman Scoop, Luis Guzmán, and Desus & Mero. This is presented as relationship history, not confirmation of current endorsements or signed Sugar Rays launch agreements.
The intended benefit is efficient acquisition and repeat engagement. Actual reach, acquisition cost, conversion, and repeat-purchase data are to be supplied.
NYC first for three years. Selective U.S. regional replication follows operating proof; international expansion is an exploration after domestic validation.
Prove contribution margins, reorder behavior, customer repeat, and node payback.
Scale the domestic playbook without relying on overseas openings.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 2, 5, 22 and 30. Figures are management estimates, not audited results.
Times Square is modeled at 1,000–2,000 square feet without a production kitchen. Its capital is to be sourced outside the original Series A buildout allocation, including potential tenant improvements, rent concessions, and equipment financing. These arrangements are not assumed to be secured.
The base case excludes future owned dairy, roastery, and co-packing revenue. Those capabilities remain longer-term options after the core model is proven.
The team combines product craft, hospitality operations, coffee expertise, and brand storytelling.
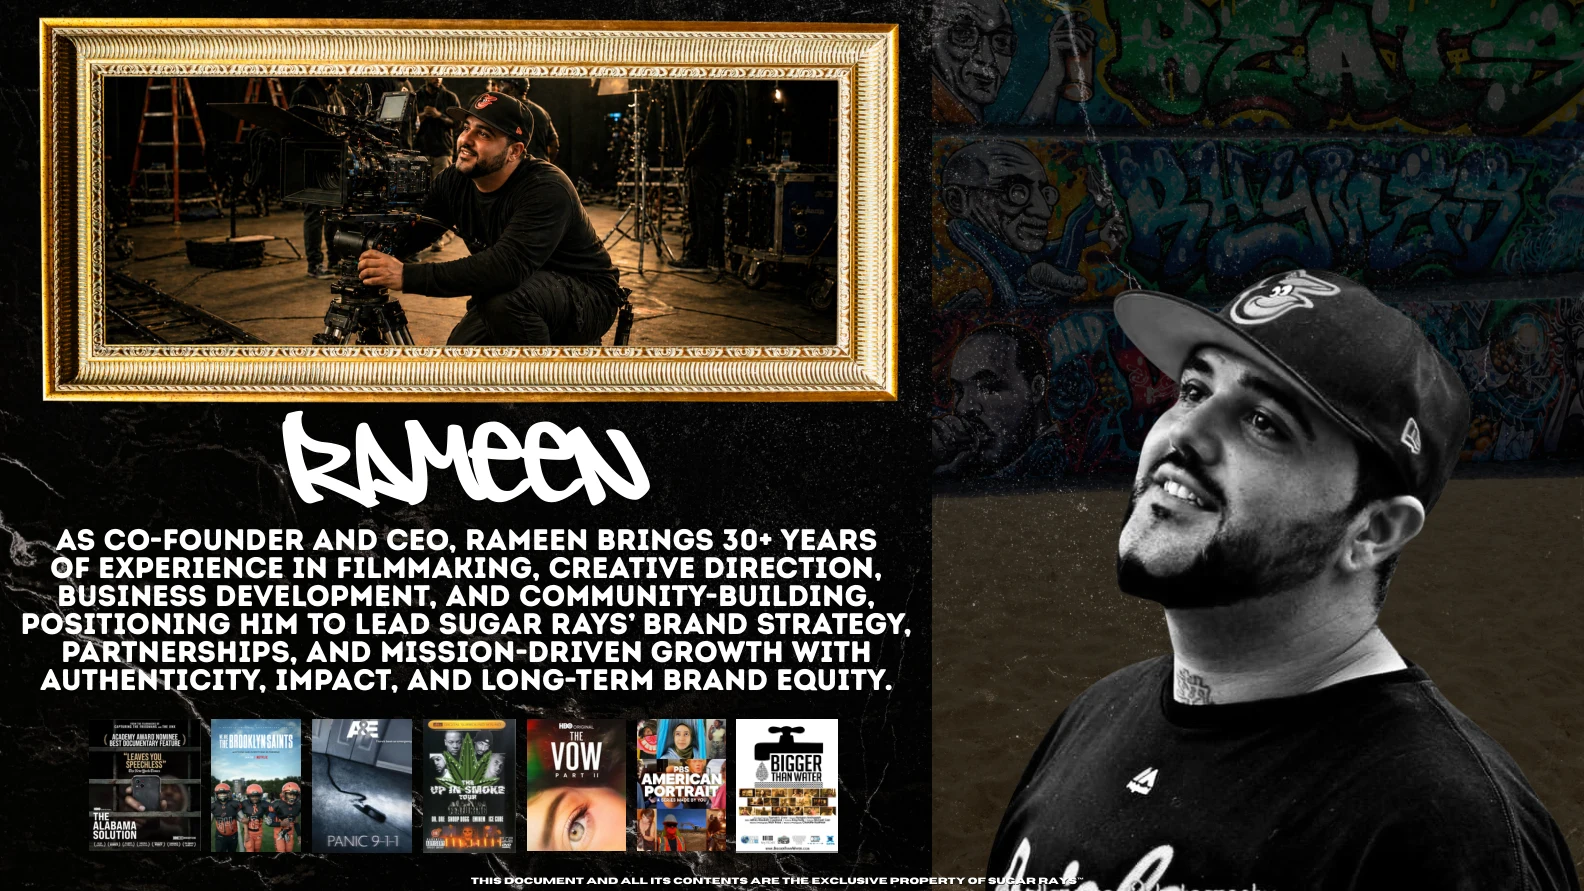
30+ years in filmmaking, creative direction, business development, and community building.
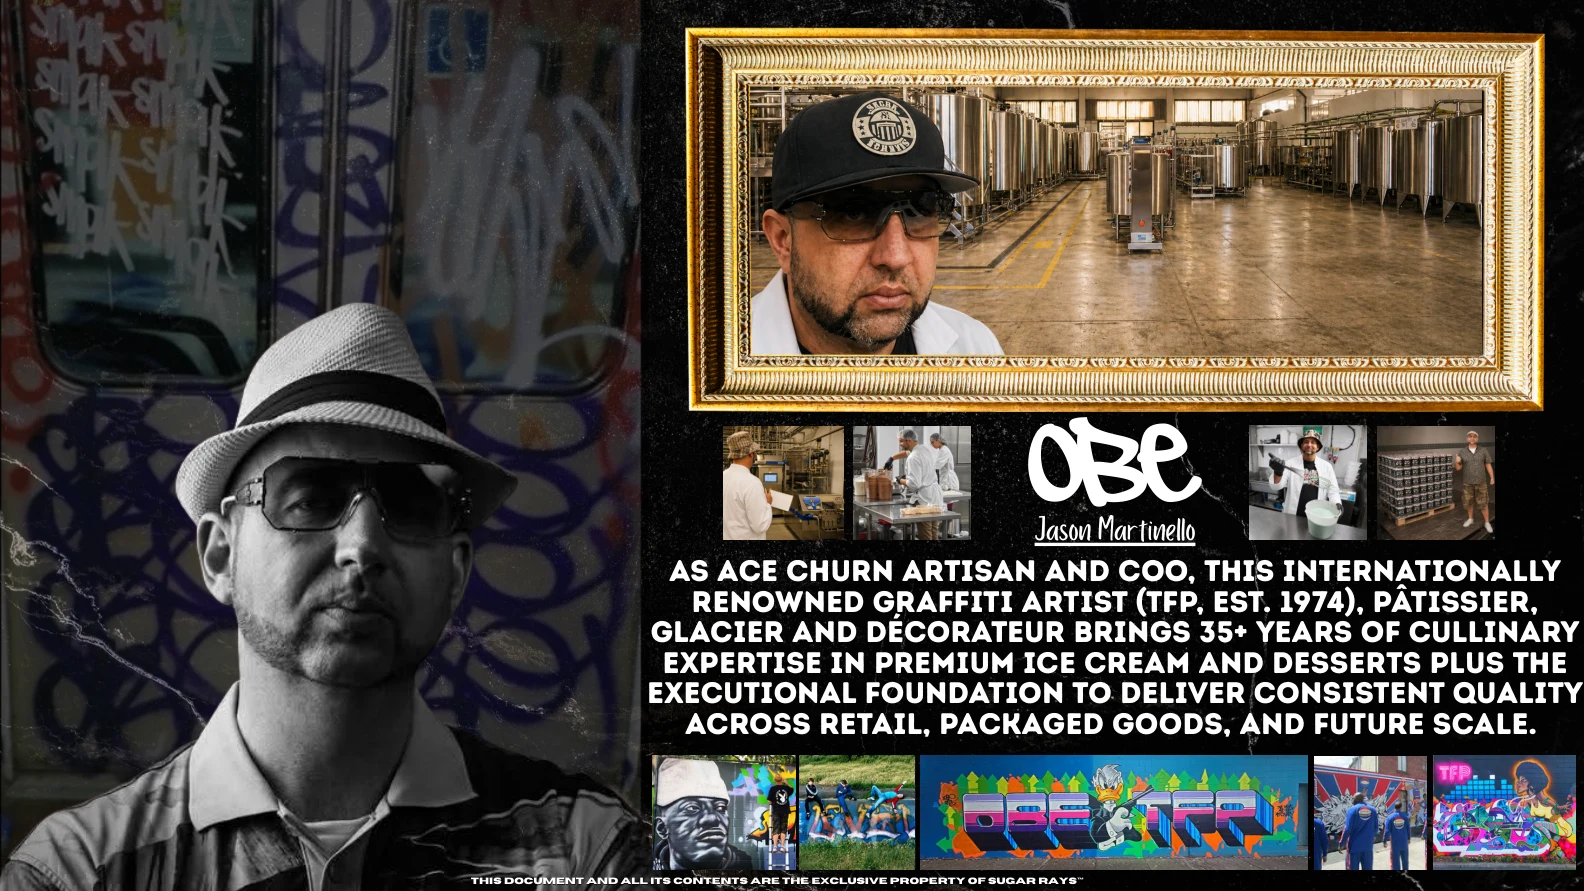
35+ years of culinary expertise in premium ice cream and desserts, alongside an internationally recognized graffiti practice.
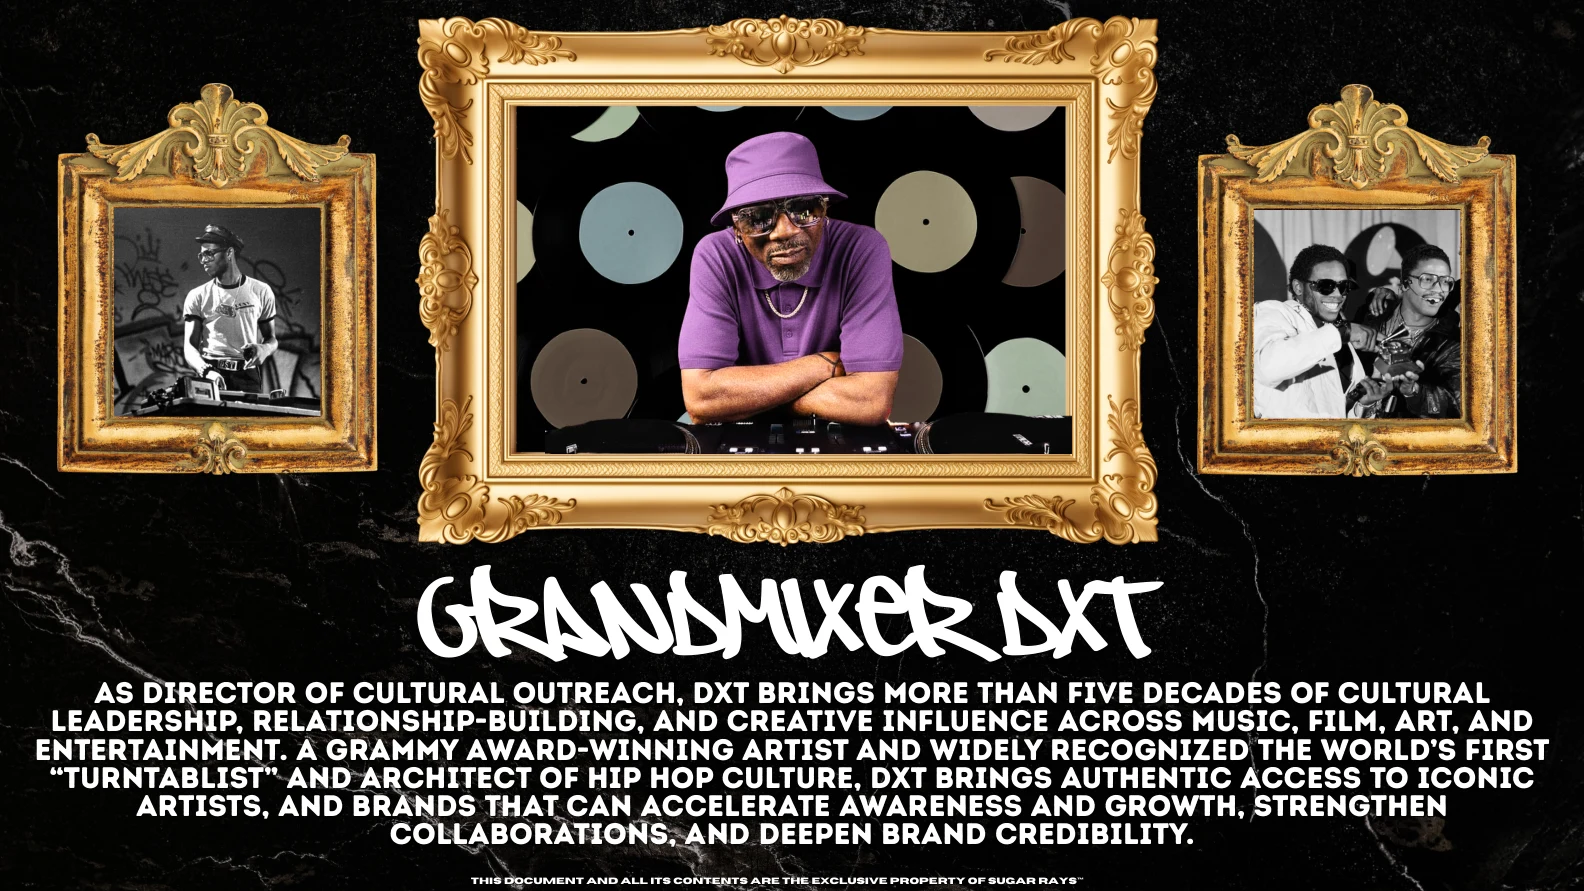
Grammy Award-winning artist with more than five decades of cultural leadership and relationships across entertainment.
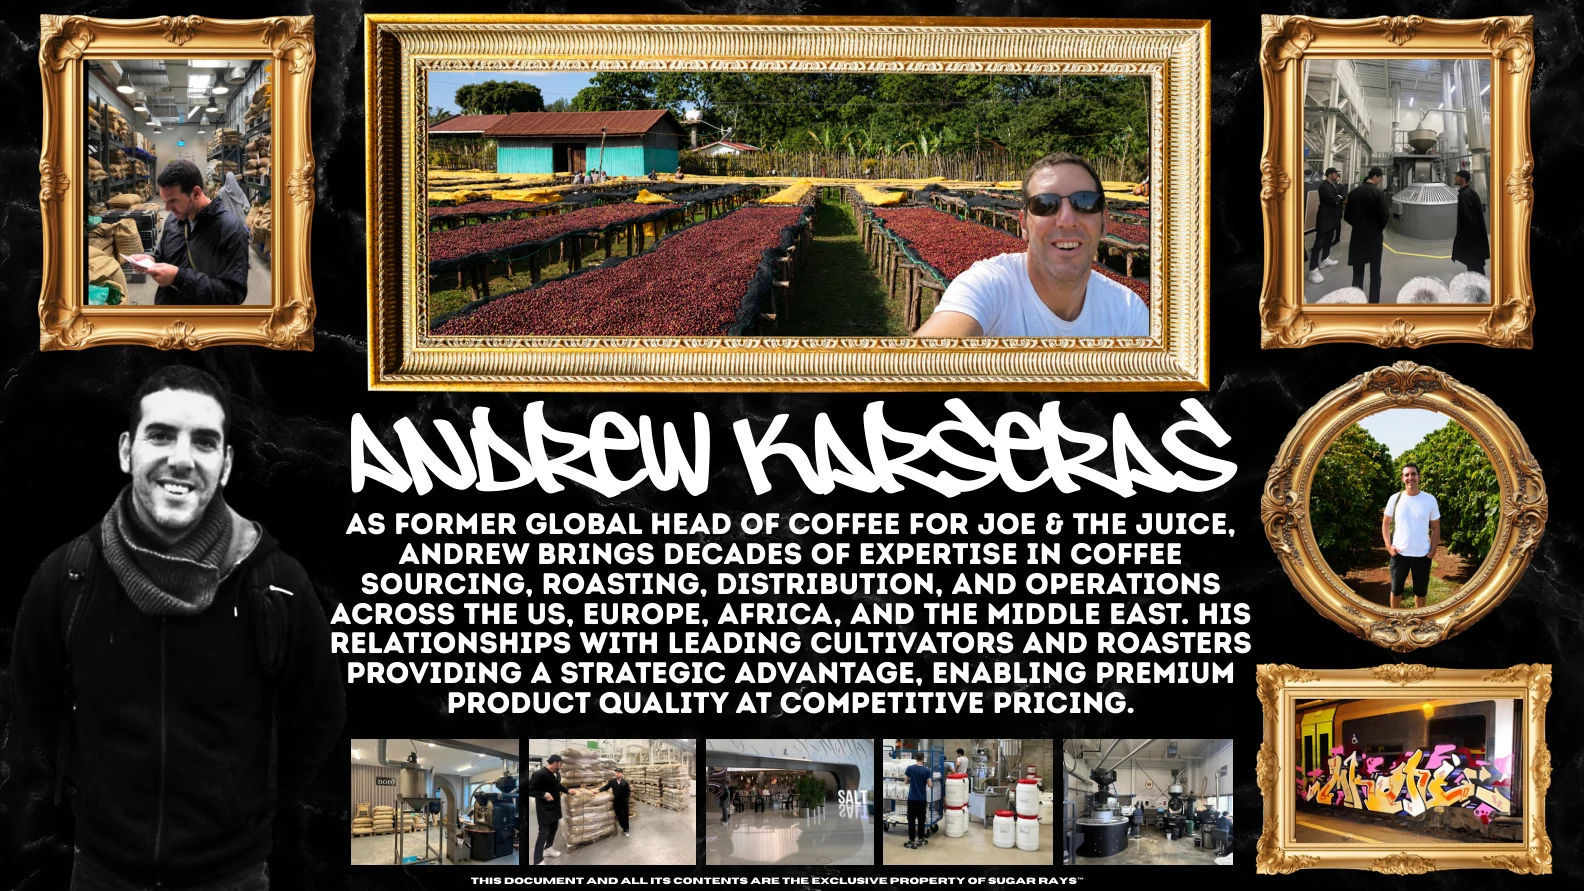
Former Global Head of Coffee at Joe & The Juice, with sourcing, roasting, distribution, and operating experience across multiple regions.
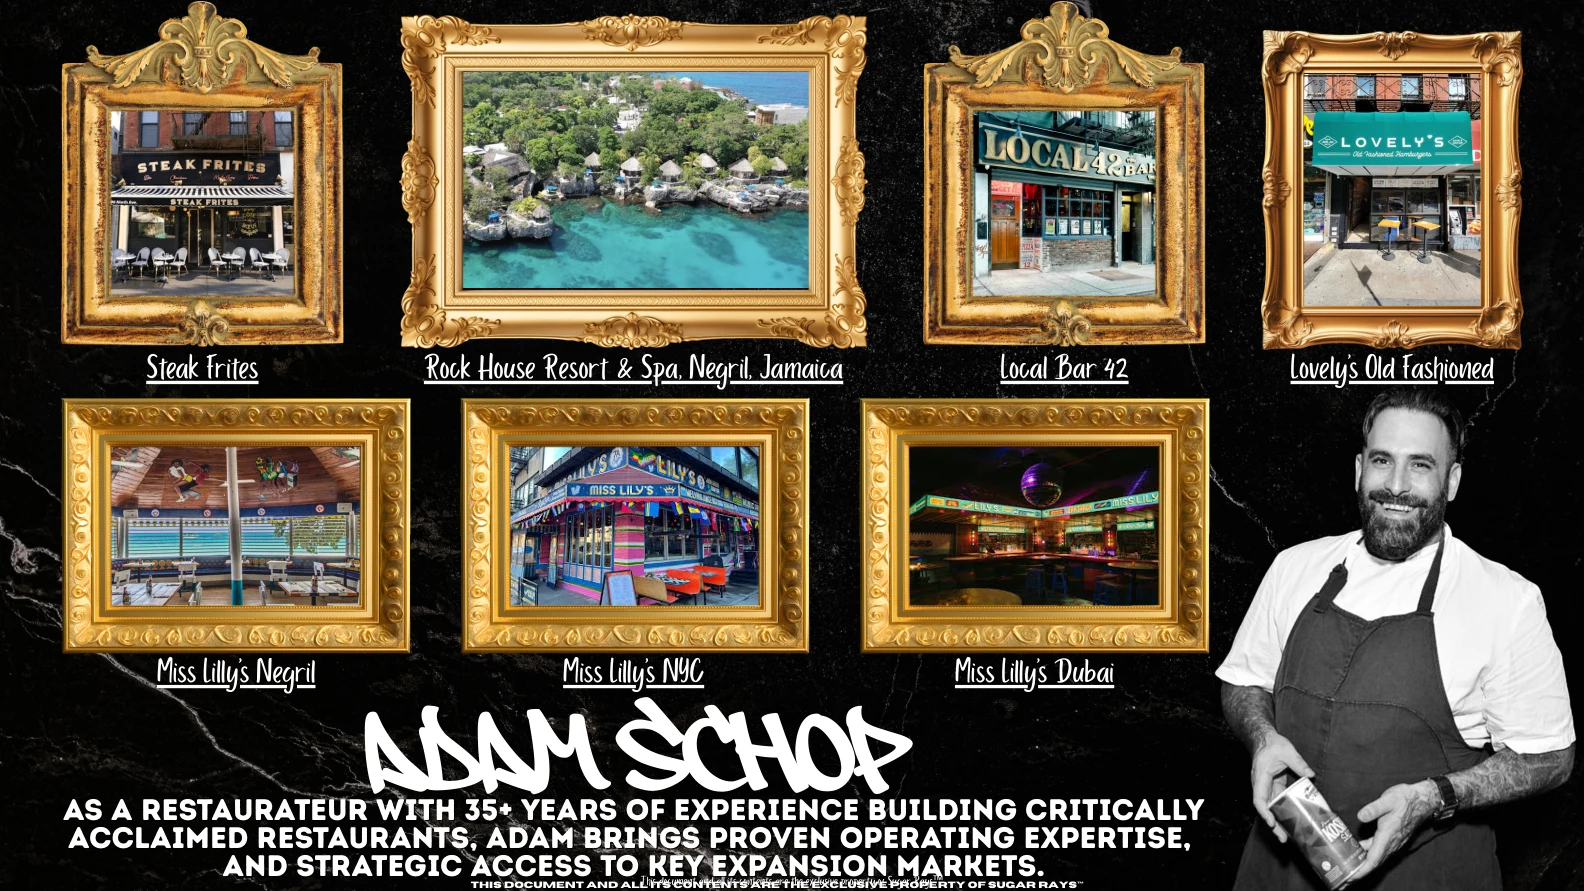
Restaurateur with 35+ years of experience building critically acclaimed restaurants and access to potential expansion markets.
Prove the NYC model first. The base case approaches EBITDA breakeven in FY2, turns positive in FY3, and scales through domestic replication.
MANAGEMENT BASE CASE · OCTOBER 2026 · UNAUDITED PROJECTIONS
| Metric | FY1 | FY2 | FY3 | FY4 | FY5 |
|---|---|---|---|---|---|
| Revenue | $2.60M | $5.55M | $9.60M | $14.60M | $22.60M |
| Blended gross margin | 68.0% | 69.0% | 70.0% | 70.5% | 71.0% |
| Gross profit | $1.77M | $3.83M | $6.72M | $10.29M | $16.05M |
| EBITDA | ($0.62M) | ($0.05M) | $0.75M | $1.90M | $3.75M |
| EBITDA margin | -23.8% | -0.9% | 7.8% | 13.0% | 16.6% |
FY labels follow the source model; fiscal-year boundaries are not specified. The base case includes no international revenue or owned dairy, roastery, or co-packer revenue. EBITDA is not cash flow or investor return.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 22–24 and 26. Figures are management estimates, not audited results.
| Product | Price / SR share | COGS | Variable GM |
|---|---|---|---|
| 4 oz scoop | $5.95 | $1.50 | 75% |
| 16 oz pint · in store | $7.99 | $3.20 | 60% |
| Hot latte | $4.95 | $1.65 | 67% |
| Classic cookie · approximately 2 oz | $2.75 | $0.75 | 73% |
| 16 oz shake | $8.95 | $2.75 | 69% |
| Restaurant dessert · Sugar Rays share | $12.50 | $1.50 | 88% |
Variable gross margins exclude labor, occupancy, and channel fees. Supplier quotes and freight inputs remain subject to validation. The restaurant figure is Sugar Rays’ share of a $25 dessert combination, not the full customer price.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 12 and 20. Figures are management estimates, not audited results.
The lease base case uses $60 per square foot of base rent plus $12 per square foot of additional rent. Lease concessions, tenant improvement contributions, construction bids, and supplier terms remain to be documented. Founder cash salaries total $350K before payroll burden. These are underwriting assumptions and target paybacks, not operating results.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 18–21. Figures are management estimates, not audited results.
Management identifies YingTao as a confirmed pre-launch placement. Miss Lily’s and Steak Frites are verbal agreements with logistics pending; two additional restaurants are discussions only. No realized placement revenue or measured customer acquisition / retention results are supplied.
The YingTao working structure is a $25 dessert combination split 50/50, with Sugar Rays supplying one 4 oz scoop. At $1.50 illustrative scoop COGS, Sugar Rays’ $12.50 share produces $11 variable gross profit before other operating costs. Volume scenarios in the book are illustrative, not actual sales.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 12–14. Figures are management estimates, not audited results.
The cash model targets 24–36 months of runway while protecting the $600K contingency. It shows FY1 EBITDA of ($0.62M), FY2 of ($0.05M), and FY3 of $0.75M. A monthly cash-flow schedule remains subject to the executed lease, construction payments, and supplier terms.
The downside scenario tests approximately 20% weaker demand, 3 percentage points of additional labor pressure, 5% COGS pressure, weaker lease concessions, and delayed regional expansion. A quantified downside P&L, verified acquisition / repeat-purchase data, and final commercial agreements remain outstanding.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 26 and 29–32. Figures are management estimates, not audited results.
A $4 million minority growth-equity round to prove the NYC system: Harlem, production, DTC, one truck, and pre-launch restaurant placements.
Preferred Series A dilution is 15–20%, with 17.5% used as the midpoint underwriting case. Final financing documents and negotiated terms control.
Total: $4,000,000. The $1.145M working-capital reserve is included in the $3.40M planned allocation; it is separate from the $600K protected contingency. Times Square buildout is not a planned Series A draw.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 2 and 25. Figures are management estimates, not audited results.
| Series A dilution | Pre-money | Post-money |
|---|---|---|
| 15% | $22.67M | $26.67M |
| 17.5% midpoint | $18.86M | $22.86M |
| 20% | $16.00M | $20.00M |
These are financing scenarios, not an agreed valuation. The book models up to 3% landlord equity tied to measurable concessions, a later 20% Series B, and a later 5% option pool. Landlord equity is intended to vest against quantified economic value rather than be granted upfront.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 18 and 27. Figures are management estimates, not audited results.
Target soft launch: March 2027 for the production hub, DTC infrastructure, and truck. Target flagship grand opening: July 2027. Dates are management targets.
A contemplated $16M Series B finances staged regional replication and additional capacity after NYC proof. It is tied to stable Harlem contribution, a viable Times Square spoke, positive frozen-DTC contribution and repeat demand, restaurant reorders, CPG velocity, and collaboration conversion. The base case does not rely on Series B to keep Harlem solvent.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 2, 5, 22 and 30. Figures are management estimates, not audited results.
The book tests hypothetical exit equity values, not forecasts or guaranteed outcomes. The scenarios assume 12.901% fully diluted Series A ownership at exit and a $4M initial investment.
| Exit equity value | Series A proceeds | MOIC | 5-year IRR | 7-year IRR |
|---|---|---|---|---|
| $150M | $19.4M | 4.84× | 37.1% | 25.3% |
| $300M | $38.7M | 9.68× | 57.4% | 38.3% |
| $500M | $64.5M | 16.13× | 74.4% | 48.8% |
Assumptions exclude net debt, preference stacks, taxes, and transaction costs. Actual proceeds depend on financing terms, dilution, business performance, and an exit. Potential routes include a strategic sale, sponsor secondary / recapitalization, or a PE-backed continuation; an IPO is long-duration upside outside the base case.
Source: Sugar Rays PE Investment Book · October 2026, printed pages 27–28. Figures are management estimates, not audited results.
Request a conversation about the Sugar Rays opportunity, launch plan, and financial model.
sugarraysnyc@gmail.comConfidential investor presentation. Financials are management projections, not audited results. Not an offer to sell securities. Meeting requests are subject to confirmation.